It all starts with understanding shopper sentiment and choice drivers. Despite a rebound in consumer sentiment during the first quarter of 2024, as of the end of last year consumer sentiment had yet to fully recover to pre-pandemic levels.1
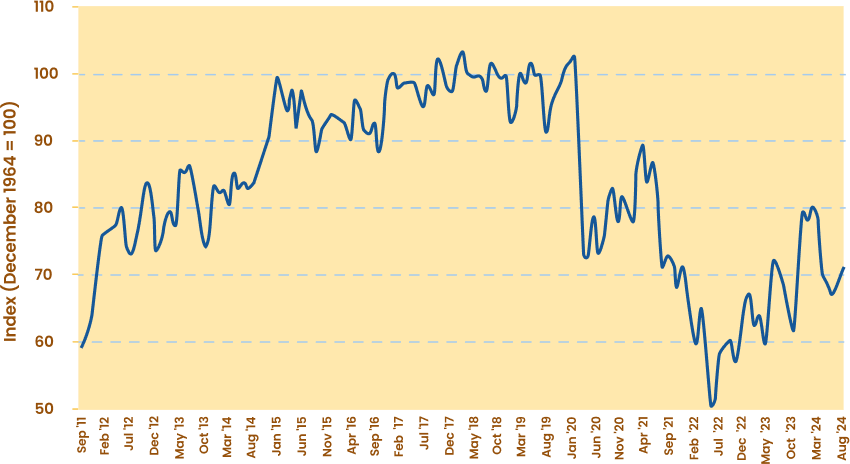
And that means shoppers continue to make tradeoffs, with dining out and entertainment being the categories shoppers are the most likely to reduce spending in. The good news is that shoppers are far less likely to reduce spending on groceries.2
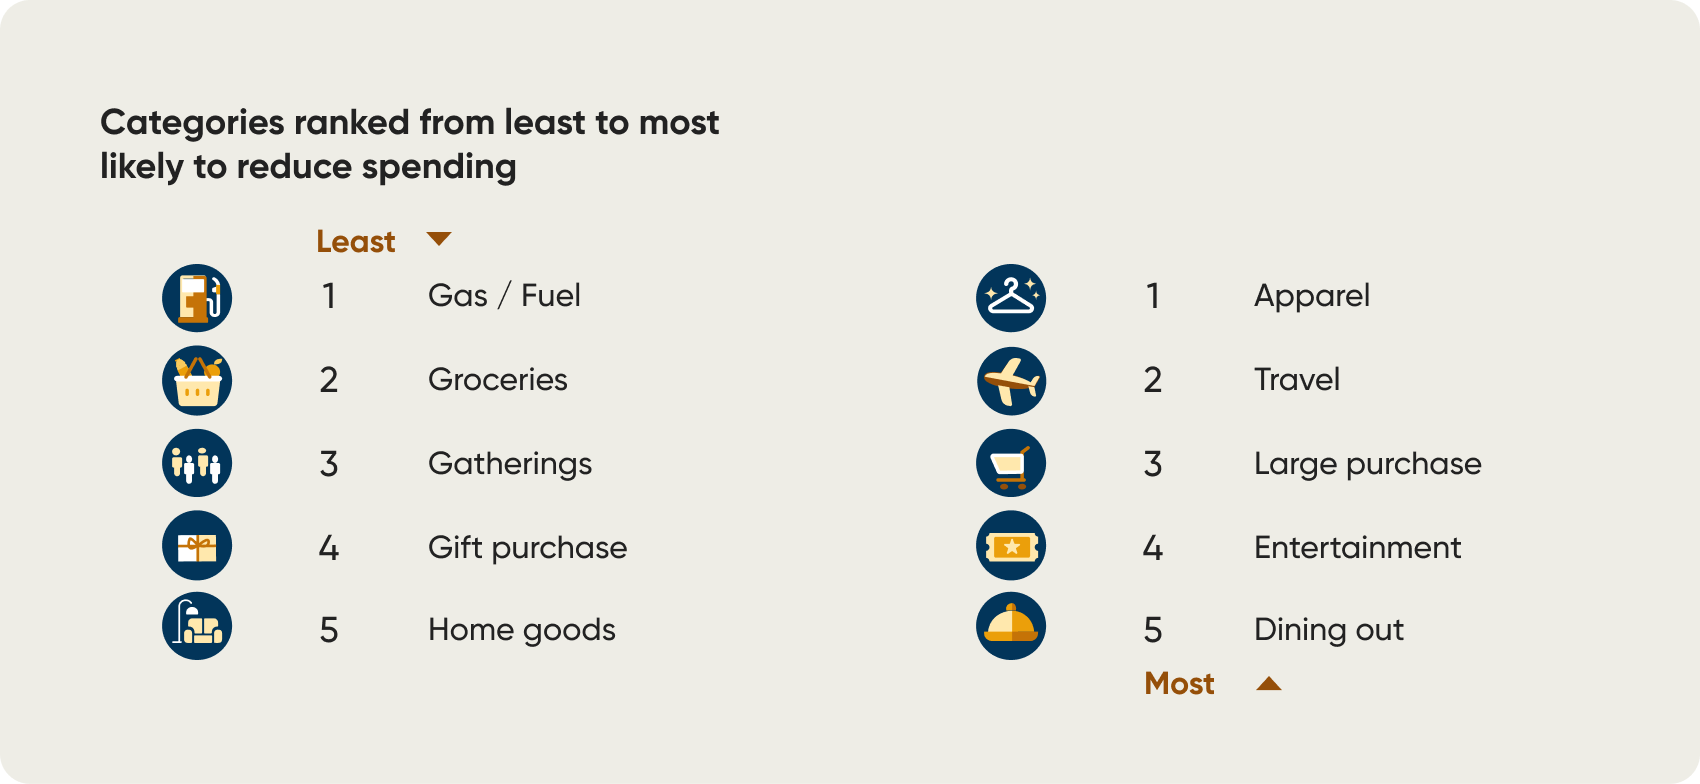
So which categories are expected to grow? Are there any household dynamics to be aware of heading into this new year? And what does the landscape look like in terms of shopper
Insight #1
Core food & beverage categories are
projected to grow in 2025
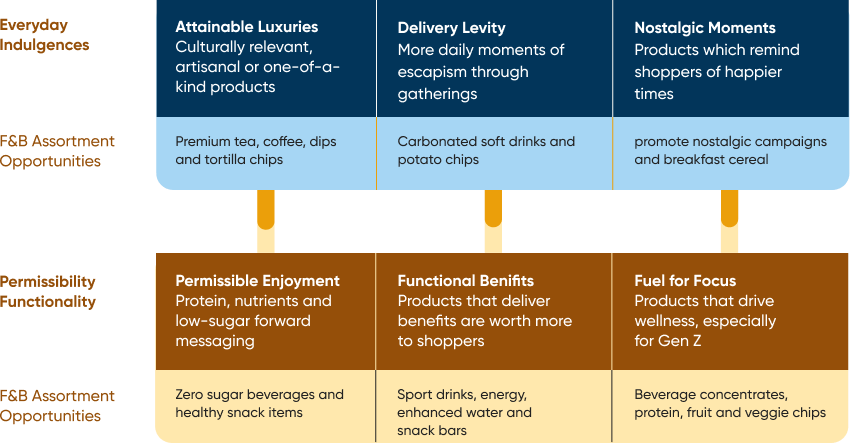
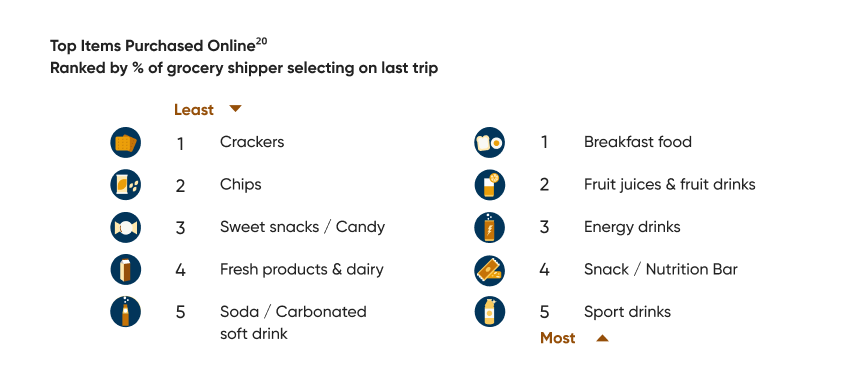
Despite headwinds, shoppers remain less likely to make tradeoffs on food & beverage items. In fact, key categories are expected to grow. About half of Americans snack 3+ times a day3 and salty snacks are expected to grow at a 5-year CAGR of 4.0%.4 Similarly, beverage consumption is up 5% vs. pre-COVID.5 It too is expected to grow 3.8% over the next five years.6 Finally, breakfast is hot, with 33% of all edible trips expected to include a breakfast food item.7
Insight #2
Households without kids are an often-overlooked growth opportunity
Another factor to consider is household purchasing dynamics. Families with kids will continue to drive spending and trips in edible food, having contributed more to growth than households without kids in 2024.8 That said, it’s important to realize that households without kids are more numerous and spend more, overall than households with kids, so it will be important to capture more of their share of spend in 2025 if they’re not to be left behind.9
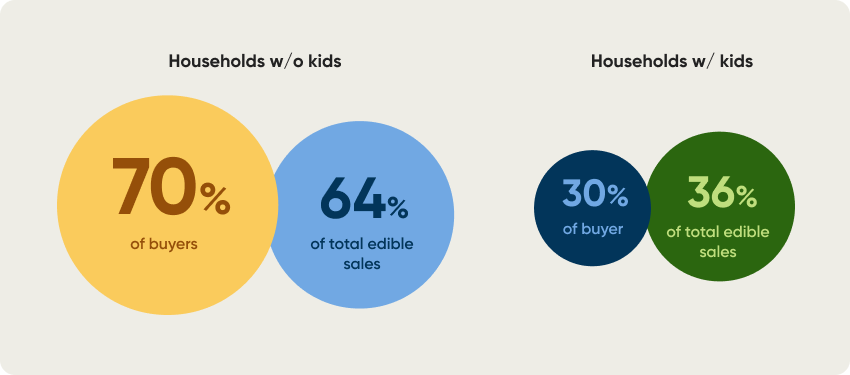
The reason why households without kids under index in edible sales is in part due to the fact that households without kids are 10% less likely to cut back on dining out than those with kids. However, there is opportunity to continue driving growth in key channels where households without kids spend more than households with kids: in Grocery & Dollar (where they spend 2x) and in Drug (where they spend 2.6x).10
Insight #3
Number of channels & retailers shopped remains high in 2025
Almost half of food & beverage shoppers now shop multiple channels, up from less than one-third pre-COVID.11 Shoppers continue to buy across a variety of different channels based on their evolving needs. In 2024, shoppers averaged close to 17 different retailers shopped with Grocery (+3.5%), Dollar (+0.6%), Convenience (+0.5%) and Club (+0.1%) all seeing increases in the number of retailers shopped vs 2023.12
So what will it take to win in 2025 with inflation-disrupted, income-constrained, and more discerning shoppers who are still on track to increase their food & beverage purchases?
In times of great change, it’s important to get back to basics. So let's tap the latest data and insights to win over new shoppers, earn their loyalty, and ensure their needs are met, unlocking brand new opportunities for growth.